How Back-to-School Season Impacts Your Household Budget and Mortgage Planning
Back-to-School Budgeting and Your Mortgage Strategy
September brings a noticeable change in pace. Between purchasing school supplies, managing extracurricular fees, and adjusting to autumn routines, household budgets often experience a sudden shift. This seasonal surge in spending frequently reveals broader financial patterns, making it an ideal time to assess long-term goals.
Examining how back-to-school expenses affect monthly cash flow provides a clear view of overall financial health. Beyond short-term purchases, this time of year offers a valuable checkpoint for evaluating equity growth, managing high-interest obligations, and reviewing your mortgage structure in Kamloops.
Managing Autumn Expenses and Cash Flow
September expenses often arrive all at once. Registration fees, clothing, technology updates, and seasonal maintenance can create temporary pressure on monthly cash flow. When these costs collide with existing financial commitments, everyday balance sheets can feel strained.
Rather than viewing these seasonal spikes in isolation, use them as an indicator of overall budget efficiency. When monthly expenses fluctuate, debt management strategies like consolidating high-interest credit card balances or personal loans into a lower-rate mortgage can help stabilize household finances.
Identifying Monthly Cash Flow Bottlenecks
Short-Term Debt Accumulation: Using credit cards to cover seasonal surges can result in high-interest charges if balances linger into the fall.
Unstructured Repayment Plans: Multiple recurring payments with varying interest rates complicate monthly tracking and limit savings potential.
Misaligned Amortization: Carrying high-interest consumer debt alongside a low-interest mortgage often leads to higher overall borrowing costs.
Consolidating consumer obligations into a structured mortgage refines monthly outlays, allowing families in Kamloops to redirect savings toward principal reduction, emergency funds, or long-term investments.
Turning Seasonal Planning into Long-Term Equity Growth
Managing immediate expenses is only one side of the equation. Autumn also serves as a strategic window to align family finances with future wealth creation.
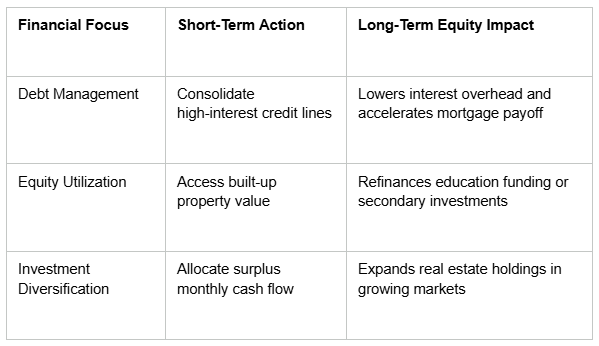
Leveraging property equity allows homeowners to address major life milestones, such as funding post-secondary education or expanding real estate portfolios, without relying on high-cost unsecured credit.
Strategic Mortgage Adjustments for Fall
As you adjust to fall routines, reviewing your home financing strategy ensures your mortgage continues to support your overall goals. A well-timed mortgage review can help keep your financial plan on track as market conditions evolve.
Key Steps for a Fall Financial Checkup
Evaluate Current Interest Rates: Review existing mortgage terms against current market rates to identify potential savings through refinancing or renegotiation.
Calculate Home Equity: Determine accessible equity built over recent years to assess refinancing options or credit line setups.
Restructure High-Interest Obligations: Combine outstanding balances into a single, manageable monthly payment to streamline cash flow.
Prepare for Upcoming Renewals: If your term matures within the next six to twelve months, start exploring options early to secure favorable terms.
Taking proactive control of your home financing creates a clear path toward financial stability through every season.
Ready to optimize your household budget and make your home equity work harder for you in Kamloops? Contact us today at +1 250-320-5555 or [email protected] to discuss your personalized mortgage options.


