Variable vs Fixed Mortgages: Why Today's Mid-4% Rates Signal a Major Market Shift
Variable vs Fixed Mortgages: Why Today's Mid-4% Rates Signal a Major Market Shift
Thinking about getting a mortgage or renewing soon in Kamloops? You have probably noticed that the mortgage conversation has flipped completely. For months, everyone was waiting on the Bank of Canada to drop rates, hoping for rock-bottom borrowing costs. But today, with benchmark fixed rates hovering around the mid-4% range and the Bank of Canada holding its policy interest rate steady at 2.25%, the market is sending us a very different message.
If you are navigating the market right now, choosing between a fixed and variable mortgage is no longer just about taking a quick discount. It is about understanding where the market is heading and securing your financial stability.
The Big Shift: Fixed Rates and Bond Yield Dynamics
To understand why fixed rates are sitting in the mid-4% range while variable rates remain tied to the policy rate, we have to look at government bond yields. Fixed mortgage rates are directly influenced by 5-year Canadian bond yields, not just the Bank of Canada's announcement dates.
Over the past few weeks, bond yields have experienced upward pressure due to broader economic forces and shifting market expectations. When bond yields rise, lenders raise their fixed rates to protect their margins. This gap creates a unique dilemma for buyers and renewing homeowners in Kamloops:
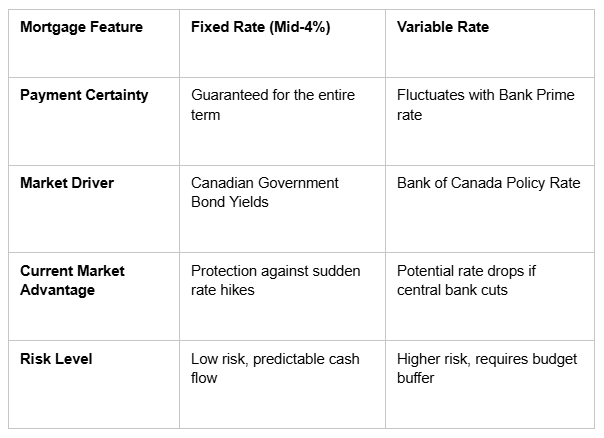
Fixed Rates (Mid-4% Range): Offer total payment predictability and peace of mind against potential future rate increases.
Variable Rates: Move in direct alignment with the Bank of Canada prime rate, offering potential initial relief if rates drop, but exposing you to upward risk if inflation ticks back up.
The mid-4% environment signifies that the era of hyper-cheap money is firmly behind us. Financial markets are pricing in long-term economic normalization rather than drastic rate cuts.
Comparing Variable and Fixed Options in Today's Market
3 Critical Factors When Choosing Your Rate Today
1. Your Household Budget Stress Tolerance
Can your monthly household budget comfortably handle a 0.75% to 1.00% increase over the next year if economic conditions shift? If a sudden payment bump would cause financial strain, locking in a fixed rate in the mid-4% range provides a guaranteed safety net.
2. The Cost of Waiting
Many buyers hold off on making purchases in Kamloops hoping fixed rates will fall into the 3% range. However, waiting carries risks. If home prices appreciate or bond yields climb further, the cost of waiting can easily outweigh any marginal rate savings.
3. Pre-Approval Rate Holds
If you are currently shopping for a home, an active rate hold is one of your strongest financial tools. A pre-approval holds your quoted rate for up to 120 days, insulating your purchasing power from market spikes while you shop.
What This Market Means for Homeowners and Buyers
Whether you are a first-time home buyer looking for your starter home, an investor analyzing cash flows, or a homeowner preparing for an upcoming renewal, strategy is everything. The shift toward mid-4% fixed rates means stress-testing your finances is essential.
Instead of trying to time the market, focus on finding a structure that matches your long-term wealth goals and monthly cash flow realities.
Ready to explore which mortgage structure fits your financial goals in Kamloops? Contact our expert team today at +1 250-320-5555 or [email protected] to schedule a personalized mortgage review!


